📘 The Policyholder’s Playbook: Wear and Tear in Real Claims
An insurance policy is a contract, and every word in it matters. Texas courts read ambiguous exclusions in the policyholder’s favor. Knowing how the “wear and tear” exclusion actually works is the first step to challenging a denial that relies on it.
What “wear and tear” actually means
Most Texas homeowners and commercial property policies exclude loss caused by wear and tear, deterioration, and similar gradual conditions. In plain English, that is the normal aging of a building:
- Paint fading over time
- Minor settlement cracks
- Roof shingles gradually shedding granules
That exclusion is legitimate. Insurance is not a maintenance contract. But property policies are written to cover sudden, accidental physical loss. When hail bruises shingles, wind lifts and creases them, or a supply line suddenly fails, that is new damage, even if the building is not new.
How the exclusion gets stretched
Before becoming a lawyer, I worked as a public adjuster and contractor. In that work I saw “wear and tear” used to explain away damage that had a clear storm-related cause, including:
- Wind-creased shingles attributed to “improper nailing”
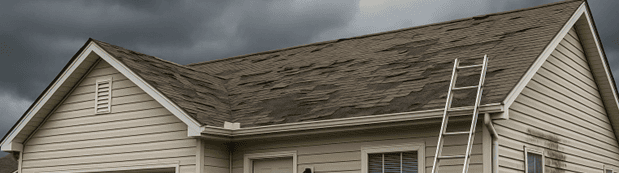
- Fresh hail impacts described as “granule loss” or “age-related deterioration”
- Storm-broken windows blamed on “thermal stress” or a “pre-existing weakness”
Not every denial is wrong. But a denial letter is the insurer’s position, not the final word.
Phrases to watch for in a denial letter
- “Normal wear and tear”
- “Wear, tear, marring, or deterioration”
- “Long-term seepage or leakage”
- “No storm-created opening”
- “Pre-existing damage”
Each of these signals that the carrier is relying on an exclusion or limitation rather than disputing that a loss happened. Under Texas law, that distinction matters.
Who has to prove what in Texas
Texas uses a burden-shifting framework. The policyholder first shows that the loss falls within the policy’s coverage. The insurer then has the burden to prove that an exclusion applies; Texas Insurance Code § 554.002 treats exclusion language as an avoidance or affirmative defense that the insurer must prove. If the insurer carries that burden, the policyholder can still show that an exception to the exclusion restores coverage.
The catch is segregation. When covered damage (for example, hail) and excluded damage (for example, wear and tear) are both present, Texas courts generally require the policyholder to show how much of the damage the covered event caused. Failing to separate the two can defeat an otherwise valid claim, which is why careful, early documentation matters so much.
Steps policyholders should take
- Document everything. Keep photos, video, dates, weather data, and prior repair or maintenance records.
- Get the decision in writing. Texas law requires an insurer that rejects a claim to give its reasons.
- Get an independent inspection. A qualified roofer, engineer, or licensed public adjuster can distinguish storm damage from aging and describe the difference in writing.
- Read your actual policy. Request a complete copy, including every endorsement. Exclusions, exceptions, and anti-concurrent-causation wording vary from form to form.
- Watch your deadlines. Many policies shorten the time to sue (Texas does not allow a contractual period shorter than two years), and Texas generally requires written notice at least 61 days before suit is filed on weather-related property claims.
Related reading
⚖️ Legal Corner: Lessons on Wear and Tear
⚖️ Legal Corner: Texas authority on exclusions and mixed causes
Tex. Ins. Code § 554.002. In a suit on an insurance contract, the insurer bears the burden of proof on any avoidance or affirmative defense, and “[l]anguage of exclusion in the contract or an exception to coverage claimed by the insurer … constitutes an avoidance or an affirmative defense.”
Gilbert Texas Construction, L.P. v. Underwriters at Lloyd’s London, 327 S.W.3d 118 (Tex. 2010). The insured must first establish coverage; the insurer must then prove that the loss falls within an exclusion; the burden then shifts back to the insured to prove an exception to the exclusion.
National Union Fire Insurance Co. of Pittsburgh, Pa. v. Hudson Energy Co., 811 S.W.2d 552 (Tex. 1991). Exceptions and limitations on liability are strictly construed against the insurer, and the insured’s reasonable reading of an exclusion controls even if the insurer’s reading appears more reasonable.
Balandran v. Safeco Insurance Co. of America, 972 S.W.2d 738 (Tex. 1998). Construing an ambiguous exclusion in the Texas HO-B homeowners form, the Supreme Court of Texas adopted the insureds’ reasonable reading and held that foundation damage caused by a plumbing leak was covered.
Wallis v. United Services Automobile Ass’n, 2 S.W.3d 300 (Tex. App.—San Antonio 1999, pet. denied). Covered plumbing leaks and excluded settling both contributed to foundation damage. The insureds lost because they offered no evidence segregating the damage caused solely by the covered leaks.
JAW The Pointe, L.L.C. v. Lexington Insurance Co., 460 S.W.3d 597 (Tex. 2015). The policy’s anti-concurrent-causation language barred coverage for costs caused concurrently by covered wind and excluded flood, which shows why the exact wording of your policy matters.
Advanced Indicator & Manufacturing, Inc. v. Acadia Insurance Co., 50 F.4th 469 (5th Cir. 2022). Applying Texas law to a commercial wind claim, the Fifth Circuit reversed summary judgment for the insurer because a jury could reasonably find that all of the loss came from covered wind rather than excluded wear, tear, and deterioration.
👉 Final Takeaway
Carriers sometimes use “wear and tear” to deny damage that a storm or other sudden event actually caused. Under Texas law:
- The insurer must prove that an exclusion applies.
- Ambiguous exclusions are read in the policyholder’s favor.
- When covered and excluded causes combine, you need evidence that separates the covered damage, so document early.
- Anti-concurrent-causation wording in your policy can change the result.
If your Texas property claim was denied or reduced because of “wear and tear,” contact The Claim Attorney for a free case review.
This article is general information, not legal advice, and reading it does not create an attorney-client relationship. Results depend on the facts of each case and the language of each policy. Michael P. Bowman is licensed to practice law in Texas and Alabama.


